A good corporate gifting policy does five things: it names who is covered, sets dollar limits per gift and per year, bans cash and cash equivalents, defines when gifts are off limits (bids, reviews, officials), and says who approves exceptions and where gifts get recorded. Everything else is detail. This guide walks through each of those pieces for a US company, with real numbers from public policies and government guidance, plus a template outline you can adapt this week.
TL;DR
- Cover everyone, from the newest hire to the CEO, and both gifts given and gifts received.
- Set a per-gift limit and an annual limit per recipient. Published US examples run roughly $50 to $100 per gift.
- Prohibit cash and gift cards in any amount, and ban gifts during bids, contract talks and vendor evaluations.
- Require approval above the limit, a simple log, and a named person employees can ask.
- Treat government officials and public-sector customers as a separate, stricter category, and check the tax treatment of anything given to employees.
Table of Contents
- Why a gifting policy matters
- Who the policy should cover
- The core test: purpose, value and frequency
- Setting dollar limits that work
- Cash, gift cards and other cash equivalents
- When gifts are off limits
- Government officials and public-sector customers
- Hospitality, travel and entertainment
- Approvals, disclosure and records
- Taxes and exceptions for employee gifts
- A template outline you can adapt
- Our perspective: policy and rewards are two halves of one program
- Where travel certificates fit
- Rolling the policy out
- FAQ
- Sources
Why a gifting policy matters
Most companies only write a policy after something uncomfortable happens: a vendor sends a lavish holiday basket in the middle of a contract review, or a salesperson gives a client a trip that nobody approved. A written policy prevents those moments by answering the question in advance.
According to Fisher Phillips’ employment-law guidance, a gifts-and-entertainment policy promotes consistent, ethical relationships, reduces concerns about favoritism, and gives employees and business partners practical guideposts. The same guidance says the policy should apply to every employee, from the newest hire through the CEO. That last part matters: executives are usually the ones giving and receiving the most expensive gifts, so a policy that quietly exempts them loses credibility with everyone else.
A policy also protects the gift giver. When an employee can point to a written rule, saying “no thank you” to a client or a vendor stops being awkward.
Who the policy should cover
Decide scope first, because it shapes every later section.
- All employees and officers. No tiers of exemption.
- Gifts in both directions. Many templates only cover what employees accept. A strong one also covers what employees give to clients, vendors, partners and colleagues.
- Family members. Fisher Phillips recommends addressing family members, since a gift to a spouse or child of a decision maker can create the same appearance problem as a gift to the person.
- Contractors and agents. If someone acts on your behalf, the policy should say they follow it too.
- Colleagues and managers. Gifts between coworkers and from managers to direct reports are a separate situation, covered below.
Keep a clear line between two different programs. A compliance policy governs gifts between your company and outside parties. A recognition or rewards program governs what the company gives its own staff. They overlap on tax and budgeting but should be written as separate documents, or at least separate sections. If you are building the second, our guide on how to organize gifting programs for HR and managers covers the administration side.
The core test: purpose, value and frequency
Law-firm guidance on gift policies, including a Skadden practical guide to gifts and hospitality policies, treats purpose, value and frequency as the main risk factors. It also recommends concrete examples, because words like “modest” or “reasonable” mean different things to different people.
Turn that into three questions every employee can ask:
- Purpose. Is this meant to thank or build goodwill, or could it look like an attempt to influence a decision?
- Value. Is it under the dollar limit, and would it look fine if it were printed in a news story?
- Frequency. Has this person or company already received something from us this year?
A public company policy summarized in the research frames acceptable gifts as modest, infrequent, legitimate, transparent and lawful, not influencing or appearing to influence a decision, and consistent with the recipient’s own rules. That last point is easy to forget. Your policy may allow a $75 gift, but if the recipient’s employer bans all gifts, your gift still creates a problem. The Diebold Nixdorf gifts, entertainment and travel procedure is a public example of this structure.
Setting dollar limits that work
There is no legal number for private-sector gifts in the US. Companies pick their own. Published guidance gives a useful range.
Fisher Phillips describes common US gift limits as $50 to $100 per gift and $100 to $200 for entertainment. It also recommends annual limits, so that a series of small gifts cannot add up to something large while each one stays under the one-time cap.
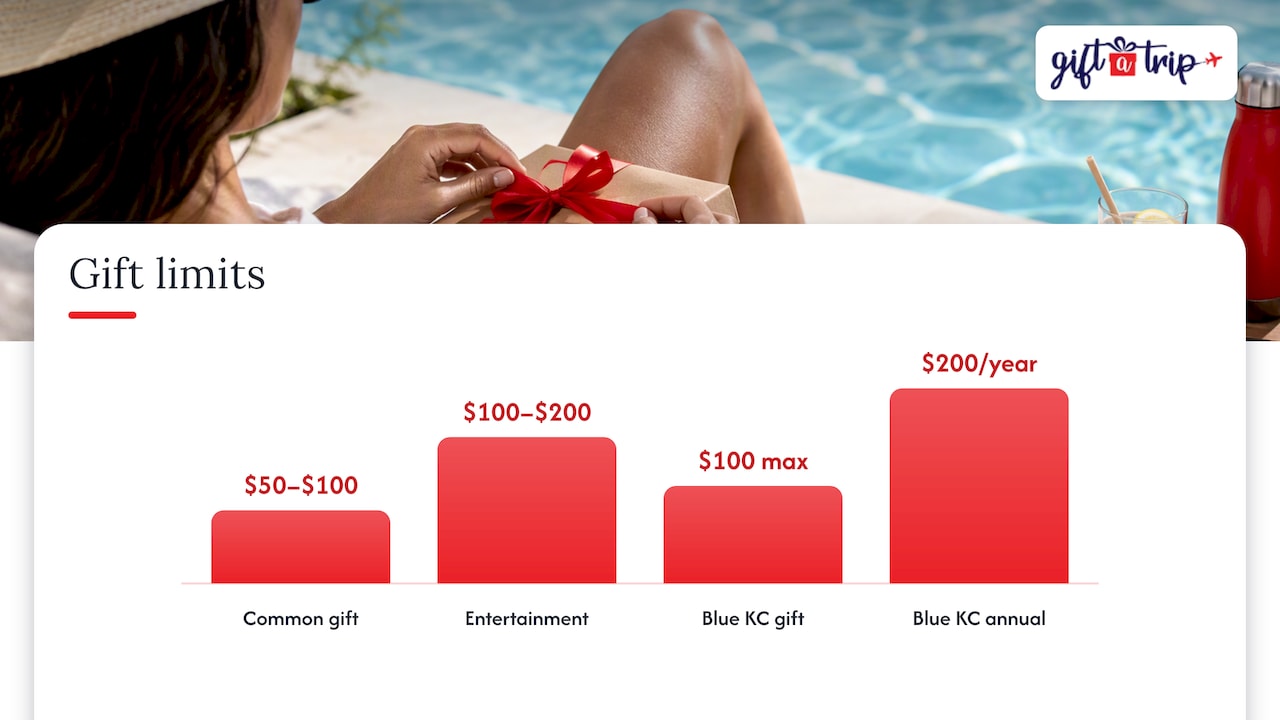
A real-world example: the Blue KC code of conduct allows gifts without prior compliance approval only when they meet its standards and are worth $100 or less per gift, with gifts exchanged with a single third party capped at $200 a year. Anything above that needs approval from Corporate Compliance.
Here is how that logic looks as a simple structure:
| Layer | What it controls | Example approach |
|---|---|---|
| Per-gift limit | Value of a single item | A fixed dollar cap, such as $100 |
| Annual limit per recipient | Total across all gifts and events in a year | A higher cap, such as $200 |
| Approval threshold | Who signs off above the cap | Manager, then compliance |
| Hard prohibitions | What no amount makes acceptable | Cash, gift cards, gifts during bids |
The numbers above are examples drawn from published policies, not a standard. Choose limits your finance and legal teams can defend, and review them when prices change. If you want a ready budgeting framework for client gifts, see our client gift budget guidelines.
Count the value correctly
Define value as the full retail or fair market value, including shipping and any bundled extras. Say how you count shared items: a bottle of wine for a team is one gift to the team, not to each person, but say so in writing. Skadden’s advice to use examples applies here too. Add a line such as “a branded notebook, a box of chocolates, a book” under acceptable, and “event tickets, jewelry, a weekend trip” under needs approval.
Cash, gift cards and other cash equivalents
This is the single rule most policies agree on. Fisher Phillips recommends prohibiting cash and cash equivalents, including gift cards, in any amount. Blue KC’s code takes the same position. The reasoning is simple: cash and cards are untraceable in purpose, easy to convert, and read as a payment rather than a gesture.
Write the rule in a way that closes loopholes:
- Cash, checks, money orders and wire transfers.
- General-purpose and prepaid cards, and gift cards redeemable for broad categories of goods.
- Securities, loans, crypto and anything else readily turned into money.
Then say what is allowed instead. Many companies permit specific, non-cash items such as a branded product, a catered lunch or an experience with a clear business or recognition purpose. Whether a specific-use certificate belongs on that list is a decision for your legal and finance teams, because the line between a cash equivalent and a specific item is a judgment call for both ethics and tax.
When gifts are off limits
Some situations are risky regardless of the price tag. Spell them out.
Bids, negotiations and reviews
Fisher Phillips recommends prohibiting gifts and entertainment during bidding, contract negotiations, vendor evaluations and formal reviews, when acceptance could look intended to influence a decision. Give your procurement and sales teams a bright line: no gifts from the day an RFP goes out until the contract is awarded and any protest period has passed.
Gifts to managers and review timing
Employee-facing etiquette guides commonly advise against giving gifts upward to superiors and against giving gifts close to performance reviews. Build both into the internal section of your policy. A manager receiving a gift from a direct report is a pressure problem even when it is sincere.
Inappropriate items
Prohibit sexually oriented, embarrassing or offensive gifts, improper favors, and anything given in exchange for something. Add a line that no gift may be solicited.
Government officials and public-sector customers
This is where a casual policy turns into legal exposure, so treat it as its own section.
Federal employees. The Department of Justice explains on its Gifts and Entertainment page that executive-branch employees generally may not solicit or accept gifts because of their official position or from prohibited sources, including entities seeking official action or business with the department. Even a permissible gift may warrant refusal if its value, timing, the donor’s interests or the access it implies could raise questions about the employee’s impartiality. Your policy should therefore say that no gift goes to a federal, state or local official without prior written approval from legal or compliance, and that the answer is often no.
Foreign officials. If you sell abroad, the DOJ and SEC’s FCPA Resource Guide says nominal gifts, reasonable meals and entertainment, and promotional items are unlikely, without more, to improperly influence a foreign official, while larger or extravagant gifts are more likely to suggest an improper purpose. It lists the hallmarks of an appropriate gift: it is given openly, recorded accurately in the giver’s books and records, motivated by genuine esteem or gratitude, and lawful under local law.
The cost of getting this wrong is illustrated in the DOJ’s closing letter in the NCH Corporation matter. There, gifts, meals, entertainment, cash and largely non-business travel for employees of a state-controlled customer were treated as potential FCPA violations because they were connected to purchasing decisions and a pending sales bid. The lesson for your policy: customers owned by a government, pending bids, cash-like benefits and mostly recreational travel are a dangerous combination, however the expense is labeled internally.
Practical rules for this section:
- Require pre-approval for any gift, meal or travel involving an official or state-owned company employee.
- Ban travel that is mostly leisure, and ban paying for family members.
- Require accurate accounting entries that describe the real purpose.
- Make clear that this section is not a substitute for advice from counsel, and that employees should contact the legal or compliance team before they act, not after.
Hospitality, travel and entertainment
Meals, event tickets and travel deserve their own line because they are often more valuable than a physical gift and harder to measure. Good policies require a real business purpose, the host’s attendance (a ticket you hand over without attending is a gift, not entertainment), and reasonable frequency.
If your company also provides ground transport for guests or executives, align that with this policy so rides, transfers and car services do not become an unreviewed perk. A corporate car service policy shows how a similar rulebook can be written for transport, and the same discipline of defined scope and purpose applies.
Approvals, disclosure and records
A rule nobody can check is a suggestion. Include the mechanics.
Per the Blue KC code, gifts above the limits need prior compliance approval, and employees must disclose gifts and entertainment accepted or offered, with business-related meals as the exception, in advance when feasible. You can copy that shape:
- Under the limit: no approval, but log anything above a token value if it comes from a single source repeatedly.
- Over the limit: written approval from the manager and compliance before giving or accepting.
- Cannot be declined gracefully: accept on behalf of the company, report it within a few days, and let compliance decide whether to return it, share it with the team or donate it.
- Records: keep a simple register with date, giver, recipient, description, value and business reason. Review it quarterly.
Fisher Phillips also advises telling employees where they can get guidance. Name a role, not just a department: “the Chief Compliance Officer or the General Counsel”, with an email address.
Taxes and exceptions for employee gifts
When the recipient is your own employee, tax rules matter as much as ethics. The IRS explains on its de minimis fringe benefits page that cash and cash-equivalent benefits cannot be treated as de minimis and should be included in wages and subject to withholding. A certificate for a specific item of minimal value may be excludable if it is provided infrequently and accounting for it would be administratively impracticable, depending on the facts.
That has two consequences for your policy. First, a gift card to an employee is not a tax-free thank you. Second, anything with real value, such as a trip, needs a tax decision made before it is awarded, not after payroll closes. Have your payroll provider or tax adviser confirm the treatment of each program. For more background, see our 2026 guide to employee gift tax rules and our explainer on how taxes are handled in travel certificates.
A template outline you can adapt
Use this skeleton as a first draft, then have counsel review it.
- Purpose and scope. Why the policy exists, who it covers, gifts given and received.
- Principles. Purpose, value, frequency, transparency, legality.
- Limits. Per-gift cap, annual cap per recipient, how value is counted.
- Prohibited items. Cash, cash equivalents, offensive items, gifts in exchange for favors.
- Prohibited timing. Bids, negotiations, evaluations, reviews.
- Officials and state-owned entities. Pre-approval, no leisure travel, accurate records.
- Hospitality and travel. Business purpose, host present, reasonable frequency.
- Approvals and records. Thresholds, register, review cadence.
- Employee recognition. Link to the separate rewards program and tax guidance.
- Questions and violations. Who to ask, how to report, consequences.
Keep the final document short enough that people read it, ideally two to four pages, with a one-page quick reference for managers.
Our perspective: policy and rewards are two halves of one program
We work with HR and sales leaders who want to reward employees and thank customers with travel, and the same question comes up every time: “How do we do this without creating a compliance headache?” Our answer is that a gifting policy should not exist to discourage generosity. It should make generosity easy to defend.
What we see work best is a clear split. Outside parties get modest, documented, non-cash gifts under defined limits. Employees get recognition through a structured program with its tax treatment settled in advance. When a reward is a travel certificate for a resort, cruise or vacation package, it has a specific purpose and a clear experience behind it, which is easier to explain and record than a pile of loose cards. We also include taxes and fees in the certificate rather than leaving them for the recipient, which keeps the gift matching what you approved. Whatever you choose, write the rules first, then pick the gift.
— Donovan
Where travel certificates fit
For internal recognition, travel is one of the gifts employees remember, and it can sit comfortably within a policy that bans cash and gift cards for being too fungible. Gift A Trip sells digital and physical travel certificates for resorts, hotels, cruises and vacation packages, with no minimum order, taxes and fees included, secure digital delivery and options for custom-branded gift boxes and trip selection sites for larger programs. You can browse the full certificate catalog, or see the corporate gifting options for bulk and branded programs.
Before you order, check the amount against your own limits and have your tax adviser confirm how the award is treated for employees. Our guides on how to gift employee travel and on holiday travel gifts for HR buyers explain the steps.
Rolling the policy out
A policy that lives in a shared drive does nothing. Launch it deliberately.
- Announce it before the holiday season, when gift volume peaks and conflicts surface.
- Train with examples. Run through five real scenarios: a vendor lunch during an RFP, a client’s holiday basket, a gift from a direct report, a trip offered by a supplier, a gift for a county official.
- Ask for annual acknowledgment. A short sign-off each year keeps it fresh.
- Audit lightly. Review the register each quarter and look for repeat givers and patterns near contract dates.
- Revisit limits yearly. Prices rise, and a limit set years ago may now ban a modest item.
FAQ
What is a reasonable dollar limit for a corporate gift?
There is no legal figure for private business gifts. Published US guidance cites $50 to $100 per gift, and one health insurer’s code uses $100 per gift with a $200 annual cap per third party. Pick a number your legal team can defend, and add an annual cap.
Can employees give or accept gift cards?
Most policies say no. Guidance from employment lawyers recommends banning cash and cash equivalents, including gift cards, in any amount. For employees on your own payroll, the IRS also treats cash equivalents as taxable wages.
Does the policy cover gifts we give to clients, not just ones we receive?
It should. Gifts given can create the same appearance of influence as gifts received, especially during a bid or with government-owned customers. Cover both directions and require approval above your limit.
Do we need a separate rule for government officials?
Yes. Federal ethics rules generally bar executive-branch employees from accepting gifts from prohibited sources, and the FCPA applies to gifts to foreign officials. Require legal or compliance approval for any gift, meal or travel involving an official, and check with counsel first.
Who should own the policy?
Usually compliance or legal owns it, with HR handling employee recognition and procurement and sales applying it day to day. Name one person employees can ask, and review it at least once a year.
Sources
- Fisher Phillips: Beware Vendors Bearing Gifts
- Skadden: Gifts and hospitality policy practical guide
- Diebold Nixdorf: Gifts, Entertainment and Travel Procedure
- Blue KC: Code of Conduct
- US Department of Justice: Gifts and Entertainment
- DOJ and SEC: FCPA Resource Guide
- DOJ: NCH Corporation closing letter
- IRS: De minimis fringe benefits